What Is the Your First Home Scheme?
For most first-time buyers, the hardest part isn't the monthly mortgage payment. It's saving the deposit in the first place, often while paying rent at the same time.
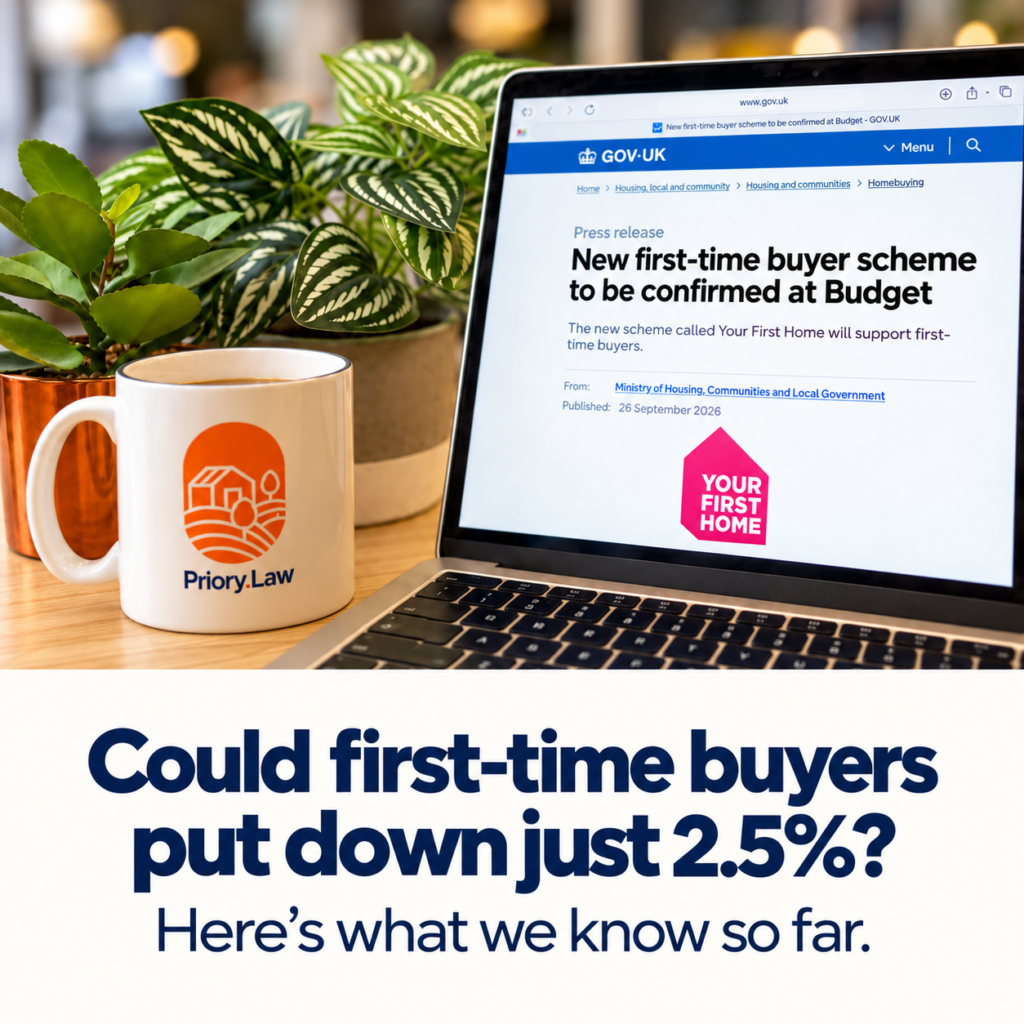
So it's no surprise that the Government's announcement on Saturday 26 September has caught people's attention. A new scheme called Your First Home could help first-time buyers in England buy a new-build home with a deposit of as little as 2.5%. The full rules won't be confirmed until the Budget on 28 October. But we already know enough to explain what's being proposed, who it's meant to help, and what's still unclear.
Read the Government announcement on GOV.UK.
What Has Actually Been Announced?
Your First Home is a Government-backed equity loan scheme for first-time buyers in England. It's designed for people buying an eligible new-build home from a developer who has signed up to the scheme.
Buyers would put down a deposit of 2.5%, and the Government would lend up to 20% of the property's value through an equity loan. That loan is expected to be interest-free for an initial period. There will be household income limits and local property price caps, so the help goes to the people who need it most, and developers taking part will contribute towards the cost of running the scheme. What we don't have yet are the actual numbers: the income limits, the price caps, the repayment terms and when it will all start. Until those are published, this is something to understand rather than something to act on.
Is Your First Home Only for New-Build Properties?
Yes, based on what's been announced so far. The scheme is for eligible new-build homes bought from developers who have signed up to it. It isn't currently being offered for older or resale properties. The full eligibility rules will come at the Budget, and we'll update this article when they do.
What Could a 2.5% Deposit Mean in Practice?
Rightmove puts the average asking price of a typical first-time buyer home, one with up to two bedrooms, at £225,199. A 2.5% deposit on that would be around £5,630. Compare that with the £22,500 or so you'd need for a 10% deposit, and it's easy to see why the announcement has got people talking. The rest of the purchase would be made up of the Government's equity loan and a mortgage. That mortgage would still depend on the lender's usual affordability checks, your credit history and their lending criteria. So while a smaller deposit could help you buy sooner, it doesn't change what you'll need to afford each month. The mortgage terms, and what the equity loan could mean further down the line, are just as important.
What Are Property Experts Saying?
The early reaction from the new-build sector has been positive, with a clear message running through it: the scheme will only be as good as its design. “Any measures that help more first-time buyers access home ownership are welcome.”
Alex Slater, Director of New Homes, Rightmove
Rightmove's figures show why the sector is keen. The number of new housing developments coming to market in the first half of 2026 was the lowest on record, with 50% fewer than in the same period of 2019.
Read Rightmove's full commentary.
“A well-designed scheme has the potential to make a real difference to households who are struggling to get onto the housing ladder.”
Neil Jefferson, Chief Executive, Home Builders Federation
That word, well-designed, is the one to hold on to. Whether Your First Home really helps will come down to the detail: who qualifies, how the equity loan works over time, where the price caps are set and how easy the scheme is to use in different parts of the country.
Read the Home Builders Federation response.
What Did We Learn From Help to Buy?
It's natural to compare Your First Home with the old Help to Buy equity loan scheme, as both use Government money to help people buy new-build homes. The timing is useful, too. Earlier this month, the Government published an independent evaluation of Help to Buy, looking back at how it worked between 2013 and 2023. It found that Help to Buy did help more people buy homes in some areas and supported new housebuilding. But in areas where homes were already expensive, it pushed prices up, and many first-time buyers were still priced out. It's a good reminder that making the deposit smaller is only part of the answer. How useful Your First Home turns out to be will depend on the final rules, and on where you're looking to buy.
Read the Government's independent Help to Buy evaluation.
Anne-Marie Fowler: What First-Time Buyers Should Remember
“For a first-time buyer who has been working hard to save, the idea of needing a 2.5% deposit rather than a much larger one is understandably going to feel exciting.
However, the deposit is only one part of buying a home of course, before committing, buyers need to understand the mortgage, the equity loan, the new-build property they are buying and what that arrangement could mean for them later if they sell or remortgage. As usual the details will be important and, right now, we don’t have the full picture, but this is positive news that we certainly welcome and look forward to hearing more about in the Budget.
Buying your first home should be exciting, and good advice helps you make that decision with your eyes open. Helping First Time Buyers is a passion of mine and I was so pleased that the Government are reintroducing a mechanism to help the next generation of home owners”
Anne-Marie Fowler, Managing Director and Licensed Conveyancer, Priory Law
What Don't We Know Yet?
Quite a lot, for now. We're still waiting to hear the income limits and local price caps, how long the interest-free period will last and what the loan will cost after that. We don't yet know the repayment rules, what happens if you sell or remortgage, which lenders and developers will take part, or when the scheme will open.
All of that should be set out at the Budget. Until then, be wary of anyone talking about Your First Home as though the rules are already settled.
What Should a First-Time Buyer Do Now?
If this sounds like it could help you, there's no need to rush. The weeks before the Budget are a good time to get a clear picture of your own position. Work out what you could comfortably afford each month, talk to a regulated mortgage adviser about your options, and keep saving where you can. It's worth remembering that the deposit isn't the only cost. There are legal fees, surveys, mortgage fees and removals to think about, and possibly Stamp Duty, depending on your circumstances.
If you've got your eye on a new-build development, ask the developer whether they're planning to take part. Just don't assume a particular home will qualify until the final rules are out. And when you do find the right home, make sure you understand both the property and the scheme you're using to buy it before you commit.
That's where we come in. We'll explain the legal side of your purchase and the paperwork that goes with it, so you know exactly what you're signing. We don't advise on whether a mortgage or equity loan is the right financial choice for you, so independent, regulated financial advice is important too.
We Will Keep Watching the Detail
There's a lot to like about a scheme designed to help more people buy their first home. For now, though, the Your First Home scheme is an announcement rather than a finished set of rules, and the Budget should fill in the gaps. When it does, we'll go through the detail and explain what it means for first-time buyers in plain, straightforward language. Buying your first home should feel exciting. Knowing exactly what you're agreeing to helps keep it that way.
We understand it's personal.
Frequently Asked Questions
What is the new Your First Home scheme?
The Your First Home scheme is a proposed Government-backed equity loan scheme for first-time buyers in England purchasing eligible new-build properties from participating developers. It is expected to allow qualifying buyers to use a 2.5% deposit alongside a Government-backed equity loan of up to 20%.
Is the Your First Home scheme available now?
No. The Government announced the proposal on 26 September 2026 and says the full details will be confirmed at next month's Budget.
Is the Your First Home scheme only for new builds?
Based on the Government announcement so far, yes. The scheme is intended for eligible new-build properties purchased from developers participating in the scheme. Full rules are still to be published.
Will every first-time buyer qualify?
No. The Government has already said household income limits and local property price caps will apply, but the exact thresholds have not yet been published.
Can I use Your First Home to buy an older or resale property?
Based on the announcement so far, no. Your First Home is being proposed for eligible new-build homes bought from participating developers.
Do I still need a mortgage?
Yes. The scheme is expected to combine your deposit and the Government equity loan with a mortgage. Your mortgage application will still be subject to lender affordability and lending criteria.
About Priory Law
Priory Law is a specialist residential conveyancing firm working with clients across England and Wales, with an established office in South Nutfield, Surrey, and a new office opening in Horsham, West Sussex.
Regulated by the Council for Licensed Conveyancers (CLC Licence Number 12134), Priory Law offers a structured, transparent and personal alternative to high-volume conveyancing. Every transaction is handled by a dedicated conveyancer, with clear communication and a process designed to stay in control from instruction to completion.
Get in touch with Priory Law · Google Reviews · ReviewSolicitors
We understand it's personal.